Interest Rates and Your Investment Decisions
Understand how interest rates influence savings, borrowing, and markets, so you can make clearer, goal-focused decisions with your investment capital.
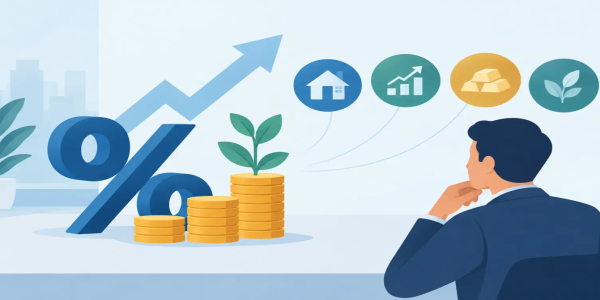
A quarter-point move can change far more than a headline. Interest rates can affect the payment on a new home, the return on cash, the value of bonds, stock market confidence, and the pace at which businesses expand. For investors building passive income, understanding this connection creates a clearer view of both opportunity and risk.
You do not need to predict every Federal Reserve decision to invest with purpose. You do need to recognize what changing rates may mean for your goals, your timeline, and the mix of assets in your portfolio. Markets often move before a rate decision is announced, which is why disciplined positioning matters more than reacting to noise.
What Interest Rates Really Measure
An interest rate is the cost of borrowing money or the reward for lending it. When you take out a mortgage, auto loan, or business loan, the rate helps determine how much you will repay. When you hold cash in a savings account, certificate of deposit, or short-term government security, the rate helps determine what your money may earn.
In the United States, the Federal Reserve influences short-term borrowing conditions through its policy rate. Banks, lenders, and markets then adjust their own pricing based on that environment. The Fed does not set every mortgage or credit card rate directly, but its decisions can influence the broader cost of capital throughout the economy.
Rates usually rise when policymakers are trying to slow persistent inflation. Higher borrowing costs can cool consumer spending and business expansion. Rates may fall when economic activity needs support, making it less expensive to borrow, invest, and spend. Neither direction is automatically good or bad. Each creates different conditions across financial markets.
For an investor, the question is not simply, “Are rates high or low?” A more useful question is, “How could this rate environment affect the assets I own and the income I want to create?”
How Interest Rates Move Major Markets
Cash and income-focused holdings
Higher rates can make cash-based products more attractive because banks and short-term instruments may offer improved yields. For someone with a near-term purchase planned, such as a home down payment or business expense, this can be useful. Capital that needs to remain stable may have a better opportunity to earn something while waiting.
The trade-off is inflation. A 4% return may sound appealing, but its real purchasing-power benefit is smaller if prices are rising at a similar or faster pace. Cash can provide flexibility and stability, yet it may not be enough for long-term wealth growth on its own.
Bonds and fixed-income assets
Bond prices and rates often move in opposite directions. When new bonds are issued with higher yields, older bonds paying lower rates can become less desirable, which may reduce their market value. When rates fall, previously issued bonds with higher coupons can become more valuable.
Duration matters here. Longer-term bonds generally react more sharply to rate changes than shorter-term bonds. That does not make one automatically better than the other. Shorter maturities may offer less price sensitivity, while longer maturities can provide different income and capital-appreciation potential depending on the market cycle.
Stocks and business valuations
Higher rates can pressure stock prices, especially for companies valued on expectations of strong future growth. When borrowing becomes more expensive, businesses may face higher financing costs, and investors may place more value on income available today rather than earnings projected years ahead.
At the same time, higher rates do not mean every stock must fall. Financial firms can sometimes benefit from wider lending margins. Companies with strong cash flow, limited debt, and essential products may be more resilient than heavily indebted businesses. Sector selection, business quality, and valuation still matter.
Lower rates can support growth-oriented assets by reducing borrowing costs and encouraging capital to move out of cash and into investments. But low rates can also lead to overly optimistic pricing. Opportunity is strongest when market enthusiasm is balanced with careful analysis.
Currencies, commodities, and digital assets
Rate changes can also influence global markets. A comparatively higher US rate environment may support the dollar because investors seek dollar-denominated returns. Currency movements can affect international companies, imported goods, and portfolios with global exposure.
Commodities may respond to changing economic expectations, currency strength, and inflation concerns. Gold, energy, and industrial metals do not follow one simple rate rule. Their behavior depends on supply conditions, geopolitical developments, demand, and investor sentiment.
Cryptocurrencies can be particularly sensitive to liquidity and risk appetite. When money is inexpensive and investors are willing to take on more risk, digital assets may see increased demand. When rates rise and uncertainty grows, volatility can intensify. Crypto exposure can offer diversification potential, but it requires a clear understanding of its substantial price risk.
Why Rate Expectations Matter as Much as the Decision
Markets are forward-looking. By the time the Fed announces a rate change, investors may have already priced in much of the expected move. The larger market reaction often comes from what policymakers signal about the future: whether more increases are likely, whether cuts may be delayed, or whether inflation is proving harder to control.
This is why dramatic, last-minute portfolio changes can be costly. Acting on a single headline may mean selling after a decline or buying after an advance. A stronger approach is to build a strategy that can operate across more than one scenario.
For example, an investor focused on steady short-term access to funds may prioritize liquidity and lower volatility. An investor pursuing long-term growth may accept greater market movement in exchange for potential appreciation. A balanced strategy may use different asset types so that the portfolio is not dependent on one rate outcome.
Match Your Investment Timeline to the Rate Environment
Your timeline should guide your decisions more than market commentary. Money needed within months should not be exposed to the same level of uncertainty as capital intended for a five- or ten-year goal.
For short-term goals, focus on access, capital preservation, and realistic return expectations. Higher cash yields can be useful, but avoid locking funds into a product that cannot support your withdrawal needs.
For medium-term objectives, diversification becomes especially valuable. The market may experience several rate cycles before your goal arrives, so spreading exposure across asset classes can help reduce the impact of one unfavorable move.
For long-term wealth building, rate volatility is part of the journey. Investors who remain focused on quality assets, diversification, and consistent contributions may be better positioned than those who attempt to time every policy turn. Long-term investing still involves risk, and past performance never guarantees future results, but time can provide room for a strategy to work through changing conditions.
A Managed Approach to Changing Rates
Monitoring rates is not a one-time task. It requires watching inflation data, employment trends, corporate earnings, currency conditions, technical market signals, and changing investor sentiment. That work can be demanding for people managing careers, families, or businesses.
A professionally managed strategy can help investors gain market exposure without personally executing every trade. At Budrigantrade, market monitoring and diversified investment opportunities are designed to make global financial participation more accessible for individuals and entities seeking a structured path toward financial well-being.
Management does not eliminate losses or make returns certain. It can, however, bring discipline to allocation decisions, risk review, and portfolio adjustments when conditions shift. Transparency matters too: investors should understand where their capital is allocated, what risks are involved, and how withdrawals, fees, and performance are handled.
Keep Your Focus When Rates Change
The best response to rate uncertainty is rarely panic or blind confidence. Review your goals, identify how much liquidity you need, and make sure your portfolio reflects the level of risk you can genuinely tolerate. If a market decline would force you to abandon your plan, the allocation may be too aggressive for your situation.
Interest rates will change again, as they always do. A well-considered strategy gives your capital a direction even when the headlines change every week.
Share This Post
Recent Posts
-
Practical Guide to Investor Risk Tolerance
07 Nov 2026
-
-
Artificial Intelligence Investing for Real Goals
07 Nov 2026
-
-