Pooled Accounts Versus Separate Accounts Explained
Pooled accounts versus separate accounts can shape control, fees, and reporting. See how each approach fits your passive investment goals with clarity.
A managed investment should fit the way you want to build wealth, not force you into a structure you do not understand. Pooled accounts versus separate accounts is one of the first distinctions to consider when choosing how your capital may be managed across global markets. The difference affects ownership, visibility, minimum investment levels, tax reporting, and how closely a strategy can reflect your personal financial goals.
For investors seeking passive income without the daily pressure of watching price charts, both structures can offer professional market participation. Neither is automatically better. The right choice depends on how much individual control you want, how much capital you plan to invest, and whether simplicity or customization matters more at this stage of your financial journey.
What Is a Pooled Account?
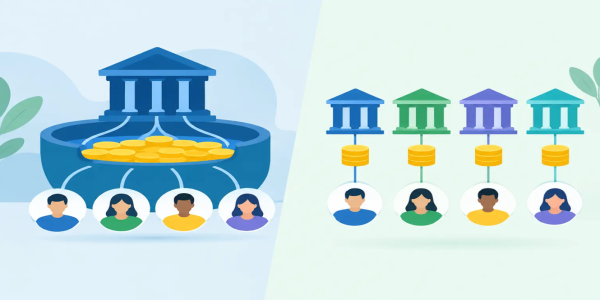
A pooled account combines money from multiple investors into one investment vehicle or shared trading account. A manager then deploys the combined capital according to a defined strategy, which may include exposure to equities, currencies, crypto assets, indices, commodities, or other market opportunities.
Each investor owns a proportional interest in the pool rather than holding every underlying position directly in an individually titled account. If you contribute 2% of the total capital, your gains, losses, and relevant costs generally reflect that 2% ownership interest, subject to the terms of the program.
This structure is common because it can make managed strategies accessible with lower starting amounts. Instead of needing enough capital to build a diversified portfolio independently, participants gain exposure to a broader strategy alongside other investors. It is designed for efficiency: one research process, one execution process, and one portfolio approach operating across the entire pool.
For a person who wants market access without actively trading, that simplicity can be appealing. The focus shifts from selecting every trade to selecting a strategy, time horizon, and manager that align with your goals.
What Is a Separate Account?
A separate account is managed for one investor or entity. The investments are held specifically for that account, and the manager trades within an agreed mandate based on the account holder's objectives, restrictions, risk tolerance, and available capital.
With a separate account, you may be able to request limits that are difficult to apply in a shared pool. For example, an investor may want to avoid a certain asset class, retain a concentrated existing holding, prioritize liquidity, or follow a specific tax-sensitive approach. The account can potentially be built around those needs rather than a single strategy serving a broad group.
That flexibility comes with practical trade-offs. Separate accounts often require higher minimum balances because individualized management, reporting, and administration require more resources. They can also involve more decisions from the investor, particularly at setup and during periodic strategy reviews.
Pooled Accounts Versus Separate Accounts: The Core Differences
The most visible difference is ownership. In a pooled arrangement, you own a share of the collective vehicle. In a separate arrangement, the assets are generally held in an account dedicated to you or your legal entity.
The second difference is customization. Pooled accounts follow one stated mandate. You choose whether to participate, but you usually do not direct individual trades. Separate accounts can allow tailored restrictions and allocations, although the amount of flexibility depends on the manager's program and operational capabilities.
Cost structure can differ as well. Pooling capital may reduce operational costs per investor because research, execution, and administration are shared. A separate account may carry higher fees or require a larger commitment to support individualized service. Investors should read the fee schedule carefully, including performance-based compensation, trading costs, withdrawal conditions, and any account-level charges.
Reporting is another major consideration. A pooled program may provide a straightforward view of your balance, performance, deposits, and withdrawals. A separate account may provide more detailed position-level reporting because the holdings are yours directly. More detail is not always more useful, however. If your priority is passive participation, a clear performance view may matter more than reviewing every transaction.
When a Pooled Account May Make Sense
A pooled account can suit investors who want a direct route to managed market exposure without building and supervising a portfolio themselves. It is often a practical fit for working professionals, beginning investors, and people seeking to diversify beyond a single savings vehicle while keeping the process manageable.
It can also be useful when your available capital is meaningful to you but not large enough to justify a fully customized investment mandate. By participating in a larger pool, you may access diversification and active management processes that would be difficult to reproduce alone.
The key is to understand the program's mandate before funding. Ask what markets the strategy may trade, whether the objective is short-, mid-, or long-term growth, how liquidity works, and how performance is calculated. A transparent platform should make it easy to see the account activity that matters: deposits, withdrawals, current balance, historical results, and applicable charges.
At Budrigantrade, the appeal of a managed structure is straightforward: investors can pursue exposure to global markets while professional monitoring and trading execution handle the daily operational work. That convenience should still be paired with clear expectations about risk and investment time horizon.
When a Separate Account May Be Worth It
A separate account may be the stronger option when your financial situation requires individual attention. This can apply to a business entity managing operating reserves, an investor with substantial assets, or someone who has specific restrictions that a standard pooled strategy cannot accommodate.
For example, you may need scheduled liquidity for a planned acquisition, prefer to exclude cryptocurrency exposure, or want investment decisions coordinated with other holdings. These are situations where direct account ownership and a customized mandate can provide more practical control.
Separate accounts can also be helpful for investors who want detailed oversight of every position. But individual visibility should not be confused with protection from market risk. Even a carefully designed account can lose value when markets move against its positions, and past results do not guarantee future performance.
Questions to Ask Before Choosing Either Structure
The strongest decision starts with the right questions. Consider whether you need customization or primarily want disciplined management. Think about your intended investment period, how soon you may need access to funds, and how comfortable you are with market fluctuations.
You should also ask how assets are held, who has trading authority, how often account information is updated, and what happens when you request a withdrawal. If a platform offers profit-based fees, understand precisely how profit is defined, when the fee is charged, and whether losses are considered before future performance compensation applies.
For entity investors, confirm whether the account documentation, reporting, and authorized-user controls support your business requirements. For individual investors, review whether the strategy matches your personal risk capacity rather than only your return target. A higher target return can involve greater volatility, longer holding periods, or a higher chance of loss.
Control Is Valuable, but So Is Clarity
It is easy to assume that a separate account is always more sophisticated because it offers more direct control. In reality, control only adds value when you have a clear reason to use it. If you do not need custom exclusions, individual tax coordination, or account-specific liquidity planning, a pooled approach may offer a cleaner path to diversified managed participation.
Likewise, a pooled account is not simply the "beginner" choice. It can be an intentional choice for investors who value efficient access, shared infrastructure, and a clearly defined strategy. The important factor is whether the structure matches your goals, not whether it sounds more exclusive.
Before committing capital, take the time to match the account structure to the role the investment will play in your wider financial plan. Choose the option that gives you enough transparency to stay confident, enough flexibility to meet real-life needs, and a level of risk you can live with through changing markets.
Share This Post
Recent Posts
-
Practical Guide to Investor Risk Tolerance
07 Nov 2026
-
-
Artificial Intelligence Investing for Real Goals
07 Nov 2026
-
Interest Rates and Your Investment Decisions
07 Nov 2026
-