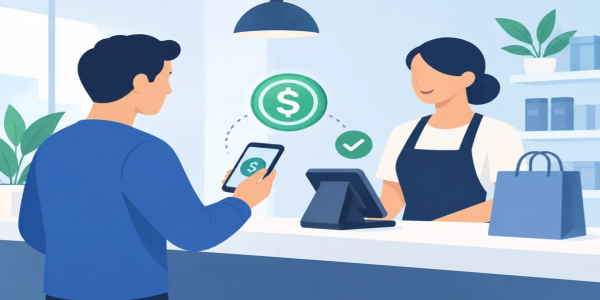
Stablecoin Merchant Payment Example: A Real Sale
See a stablecoin merchant payment example, from checkout to settlement, and learn where speed, lower fees, and customer choice can matter most today.
A customer is ready to buy a $240 product, but their card is declined for an avoidable reason: a bank flag, an international transaction rule, or a spending limit they did not know existed. With a stablecoin checkout option, the customer can pay from a crypto wallet, the merchant receives a verifiable onchain payment, and the sale can move forward without waiting on card-network approvals. This stablecoin merchant payment example shows what that looks like in practice - and where the real advantages and risks sit.
A Stablecoin Merchant Payment Example From Checkout to Settlement
Imagine an online electronics seller offering a limited-run wireless headset for $240. The store accepts card payments, but it also gives customers the option to pay in USDC, a stablecoin designed to track the US dollar.
At checkout, the buyer selects USDC. The payment page displays the exact amount, the supported network, a wallet address or QR code, and a short payment window. The buyer opens their wallet, confirms the recipient and network, then sends 240 USDC plus the network fee.
Within moments, the merchant's payment system detects the transaction. Once the required blockchain confirmations arrive, the order changes from pending to paid. The seller can ship the headset, hold the USDC in a business wallet, convert it to dollars, or exchange part of it for another digital asset according to its treasury plan.
The customer gets a payment route that is not dependent on a bank's card authorization process. The merchant gets a transaction record visible on the blockchain and, unlike a card sale, no ordinary card chargeback process. That final point matters. Payment finality can reduce certain fraud costs, but it also means the merchant needs a clear refund policy and the buyer must check payment details before sending.
Why Merchants Are Paying Attention
For many merchants, stablecoin payments are not about replacing every existing checkout method. They are about adding a faster, more flexible option for customers who already hold crypto and want to spend it directly.
A card transaction may involve authorization rules, processor fees, settlement delays, and disputes that can appear weeks after delivery. Stablecoin transactions can settle faster, particularly on lower-cost networks, and can offer a different cost structure. The result depends on the chain, wallet provider, payment gateway, conversion route, and the merchant's own operating setup.
Cross-border sales are where the difference can become more visible. A customer in another country can pay a US dollar-denominated amount without the merchant navigating foreign card acceptance issues or waiting for a traditional wire. That does not remove business obligations. Merchants still need to manage taxes, bookkeeping, consumer disclosures, sanctions screening where applicable, and the rules that govern their market. It simply gives them another rail for moving value.
For privacy-minded customers, a wallet payment can also require less personal information at the point of purchase than a typical card transaction. Merchants should be honest about the boundary: public blockchain activity is generally traceable, and a payment provider may collect information under its own terms. Privacy is not the same as invisibility.
What the Checkout Flow Should Actually Include
A stablecoin checkout should feel direct, not like a technical obstacle course. The customer needs to know three things immediately: what they are paying, which stablecoin they should use, and which network they should send it on.
The invoice should state the amount clearly, such as 240 USDC on Polygon or Ethereum. It should show a scannable QR code alongside a copyable address. If the payment address is unique to the order, reconciliation becomes far easier. If it is not, the system needs a reliable way to match the incoming amount and transaction ID to the correct customer order.
Network selection is critical. Sending USDC on the wrong chain can create a support problem that no merchant wants. Good checkout design makes the selected chain impossible to miss, warns customers not to send unsupported assets, and provides a visible countdown if the quoted amount expires after a set period.
The merchant also needs a policy for overpayments, underpayments, failed payments, and refunds. If a customer sends $239.50 instead of $240, is the order held, canceled, or accepted? If the customer requests a refund, does the business return USDC to the original wallet address or offer store credit? Set the rules before the first transaction arrives.
A simple merchant setup
A small store might price products in dollars and generate a USDC invoice only when a customer chooses crypto. This protects the merchant from having to display constantly shifting crypto prices for items that have fixed dollar costs.
Once payment is received, the business can keep some USDC for supplier payments or operating reserves, while converting the rest to fiat. A merchant that prefers market exposure could choose to convert a portion into BTC, ETH, or other assets, but that is a treasury decision - not a payment requirement. Stablecoins are often used at checkout precisely because they avoid the price swings associated with many other cryptocurrencies.
The Trade-Offs Behind the Fast Sale
Stablecoins can make payment simple, but the underlying choices are not identical for every business. A high-volume retailer may prioritize a payment processor that automates invoices, order matching, accounting exports, and dollar conversion. A crypto-native seller may prefer direct wallet acceptance to retain more control over funds.
Direct acceptance can reduce intermediaries, but it places more responsibility on the merchant. Private keys need serious protection. Wallet permissions need to be reviewed. Staff should never be able to move business funds from a personal device without controls. A hardware wallet, multisignature approval process, and separated operating wallet can be sensible safeguards depending on transaction volume.
There is also stablecoin risk. Not every token marketed as stable has the same reserves, redemption model, liquidity, or legal structure. Merchants should choose assets they understand, monitor the issuer and market conditions, and avoid treating a stablecoin label as a guarantee. A token can temporarily lose its peg, face liquidity pressure, or become unavailable on a selected network.
Fees vary as well. One chain may be inexpensive most of the time but congested during active market periods. Another may offer fast, low-cost transfers but have lower wallet support among a merchant's customers. The best network is the one that matches the stablecoin, the customer base, and the business's ability to receive and manage it reliably.
Where This Payment Model Makes the Most Sense
Stablecoin checkout is especially practical for online merchants with crypto-aware customers, digital product sellers, international businesses, freelancers, gaming communities, and merchants serving audiences that value payment flexibility. It can also be useful for businesses that already receive crypto through P2P transactions and want a cleaner way to track customer payments.
It may be less useful for a local business whose customers do not use wallets, or for a company that needs instant access to traditional bank settlement and lacks the capacity to manage digital assets. In those cases, a processor that converts stablecoin payments to dollars automatically may be the better fit, even if it adds a fee.
The opportunity is not to force crypto on every buyer. It is to stop turning away customers who already want to pay this way. Choice at checkout can be a competitive advantage when it is presented clearly and managed responsibly.
Turn Stablecoin Payments Into a Real Option
Merchants do not need to rebuild their entire business around digital assets to test this model. Start with one established stablecoin, one supported network, a clear checkout screen, and a defined settlement policy. Track payment completion time, support requests, network costs, refund volume, and whether crypto-paying customers spend more or return more often.
For traders and business owners who want faster access to digital assets, platforms such as Budrigan Market can support the wider crypto workflow around holding, converting, and moving value. The winning merchant payment experience is not the one with the most jargon. It is the one that lets a willing customer pay with confidence, lets the merchant verify funds quickly, and keeps both sides in control of the next move.
Share This Post
Recent Posts
-
P2P Offer Comparison: Find Better Crypto Deals
06 Oct 2026
-
Binary Trading: Know the Risk Before You Trade
06 Oct 2026
-
Account Funding Options for Faster Crypto Trades
06 Oct 2026
-
Custody Model Comparison for Crypto Traders
06 Oct 2026
-
What Makes Peer Payments Private and Secure?
23 Sep 2026