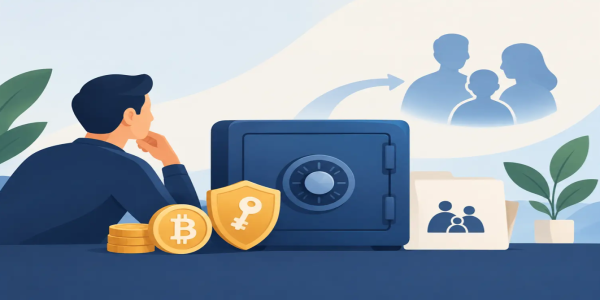
Practical Guide to Self Custody Inheritance
A guide to self custody inheritance: create a private, secure crypto succession plan without leaving your heirs locked out of the assets you own later.
If your crypto is in self-custody, no exchange, bank, or support desk can restore access after you die or become incapacitated. That freedom is the point, but it creates a serious responsibility. This guide to self custody inheritance shows how to build a clear recovery plan that protects your privacy while giving the right people a realistic path to claim what you own.
Crypto ownership is not proven by a name on an account. It is proven by control of private keys, seed phrases, wallet devices, and any passwords required to use them. If those access details disappear, the assets may remain visible on-chain forever but become unreachable in practice.
Why self-custody inheritance needs its own plan
Traditional inheritance systems were built around institutions. A bank can identify an account holder, freeze an account after a death certificate is presented, and transfer funds through an estate process. Self-custody works differently. Your wallet does not know who you are, who your beneficiaries are, or what your will says.
That means a will alone may not be enough. Your executor may legally inherit the assets yet have no technical way to move them. On the other hand, placing a seed phrase directly in a will can create a different problem: wills can become part of probate records, and too many people may gain access to sensitive information.
The objective is not to give away control today. It is to create a controlled handoff for a future event. A good plan balances three competing priorities: your assets must stay secure while you are alive, your instructions must be understandable when you cannot explain them, and your heirs must be able to act without exposing the wallet to unnecessary risk.
Start with an honest inventory
Most inheritance failures begin with incomplete information. People remember their major Bitcoin or Ethereum holdings but forget an older wallet, a hardware device in a drawer, a stablecoin position, or funds tied up in a staking protocol. Your heirs cannot recover assets they do not know exist.
Create a private inventory of every place where you hold crypto. Include wallet type, which assets are stored there, approximate values, the network involved, and any dependencies. A wallet holding USDC on Ethereum is not the same as USDC on Solana. Sending or recovering assets on the wrong network can create a costly mistake.
Your inventory should also identify whether funds are held in a hardware wallet, software wallet, multisignature setup, smart contract, exchange account, or decentralized finance protocol. Do not put seed phrases or private keys in this document. Treat it as a map, not the vault itself.
Keep the inventory current. A plan written when you owned two assets can become useless after months of trading, conversions, or moving funds between wallets. Review it at least once a year and after any major change in your holdings or security setup.
Separate legal authority from wallet access
Your estate documents should name the people who are authorized to handle your digital assets. Depending on your situation, that could be an executor, trustee, spouse, adult child, or another trusted person. A qualified estate attorney can help make sure your will, trust, and powers of attorney reflect applicable state law.
But legal authority and technical access are separate layers. Your estate plan can tell a person they have the right to manage the assets. Your crypto inheritance plan tells them how to find the assets, verify what they are looking at, and obtain the access information without improvising.
Avoid naming a beneficiary without discussing the responsibility involved. Receiving crypto can be simple. Securing a seed phrase, signing a transaction, dealing with volatility, and understanding taxes may not be. If a beneficiary is not comfortable with digital assets, your instructions should offer a practical route, such as moving assets to a new wallet under their control or working with a trusted professional after access is recovered.
Build a secure access package
A self-custody inheritance package should be understandable to a nontechnical person while keeping the most sensitive secrets protected. The exact design depends on the value of your holdings, your technical confidence, and the reliability of the people involved.
For a straightforward setup, leave clear written instructions explaining what devices, documents, and locations matter. State the wallet brand or application, where the hardware wallet is stored, where the recovery material is stored, and who should be contacted first. Explain that no one should enter a seed phrase into a website, text message, email, or unsolicited support chat.
Your seed phrase should be stored offline, never in a cloud note, screenshot, email draft, or ordinary password manager. A durable physical backup may reduce the risk of loss from a failed device, fire, or forgotten password. Store it in a secure location that your chosen successor can access only at the right time.
For larger balances, a single seed phrase in one location may be too much of a single point of failure. You might split responsibilities across trusted parties, use a multisignature wallet, or store recovery components in separate secure locations. These approaches can reduce the damage of theft or loss, but they also raise complexity. A complicated setup that no heir can operate is not an inheritance plan.
Choose the right level of complexity
There is no universal best setup. A simple wallet and well-protected recovery phrase may be enough for someone with modest holdings and one highly trusted heir. A multisignature arrangement may make more sense for substantial assets, a family treasury, or an owner who wants no individual to control everything alone.
Multisignature wallets require several keys to approve a transaction. For example, a two-of-three structure can allow recovery if one key is lost while preventing one person from moving funds unilaterally. The trade-off is operational discipline. Your heirs need to know where the keys are, how many approvals are required, and how to use compatible wallet software.
Some people consider dead-man switches or automated inheritance tools. These can be useful in narrow cases, but they introduce their own risks. A missed check-in, software failure, security breach, or poorly configured trigger could expose assets too early or lock them at the wrong moment. Do not rely on automation unless you understand its failure modes and have tested the process.
Write instructions your heirs can actually use
Your instructions should be calm, direct, and specific. Assume the person reading them has never used a hardware wallet and may be under emotional pressure. Explain what not to do as clearly as what to do.
A useful instruction letter can cover these five areas:
- How to locate the asset inventory and identify the relevant wallet.
- Who has legal authority and who should be consulted before any transfer.
- Where recovery materials, devices, and passwords are stored, without placing every secret in one document.
- Basic security rules, including never sharing a seed phrase with anyone claiming to offer support.
- The intended next step, such as transferring assets to a new wallet, holding them, or seeking qualified legal and tax guidance before selling.
Use plain language. Replace vague statements like “my crypto is safe in cold storage” with details your successor can act on. If you use a hardware wallet, identify the model and explain that the device itself is not enough without the recovery process. If you use a passphrase in addition to a seed phrase, make sure your plan accounts for it. A missing passphrase can make a correctly recovered seed display an empty wallet.
Test the plan without exposing the secrets
An untested inheritance plan is only a theory. Test your instructions with a small amount of crypto or a spare wallet. Ask a trusted person to follow the process far enough to confirm they understand the inventory, the device, and the recovery path. They do not need unrestricted access to your main holdings to identify confusing instructions.
Testing often reveals overlooked details: a device that needs a PIN, a password stored in an outdated location, a wallet app that has changed, or a beneficiary who does not know the difference between a public address and a private key. Fix these gaps while you are able to make decisions.
Review the plan after a move, marriage, divorce, death in the family, major market gain, or change in trusted relationships. Your security model should change when your life changes.
Protect privacy without creating a mystery
Privacy is a legitimate part of self-custody. You do not need to publish your holdings, expose wallet addresses broadly, or hand over your seed phrase to anyone while you are alive. But complete secrecy can become an expensive mystery for the people you intend to protect.
Share the existence of the plan with at least one trusted person. They do not need every detail today. They need to know that the plan exists, where the non-sensitive instructions are kept, and what event should activate the process. This approach preserves control during your lifetime without leaving your assets stranded later.
Self-custody gives you direct control over your financial future. A thoughtful inheritance plan extends that control beyond you, turning private keys from a single-person responsibility into a lasting financial handoff your family can use with confidence.
Share This Post
Recent Posts
-
Your Guide to Blockchain Transaction Fees
20 Oct 2026
-
-
Are Stablecoin Reserves Audited? What to Check
20 Oct 2026
-
A P2P Escrow Dispute Example and How to Respond
20 Oct 2026
-
Stablecoin Regulation Trends 2026 Explained
08 Oct 2026